For established local service businesses
A business plan built to stand up to lender questions.
Bring your operating history, funding request and forecast assumptions. I’ll turn them into a business plan for SBA-backed or conventional expansion financing, and I review it before it reaches you.
Read the full fictional sample first. I confirm fit before I take any work or payment.
- $995–$2,495
- price confirmed before work begins
- 24 hours to 14 days
- you pick the turnaround
- 2 revision rounds
- every tier
Bywater Grounds Coffee House
SBA 7(a) expansion request
| Matches the sources and uses table | Loan request | $285,000Source 1 |
|---|---|---|
| Matches the sources and uses table | Owner contribution | $57,000Source 1 |
| Sources equal uses | Total project | $342,000Source 2 |
| Needs attention | Review status | Conditional draft |
- 1Bywater sample, p. 12, Funding Request
- 2Bywater sample, p. 10, Sources and Uses, Total row
Every projected figure ties back to the model that computed it.
The quickest way to lose a lender is a number in the narrative that disagrees with the tables. So the model computes every projected figure, the plan quotes it, and a final pass ties each one back. If a figure doesn’t tie out, the plan doesn’t ship.
- 1Bywater sample, p. 10, Five Year Operating Forecast, year 1 revenue
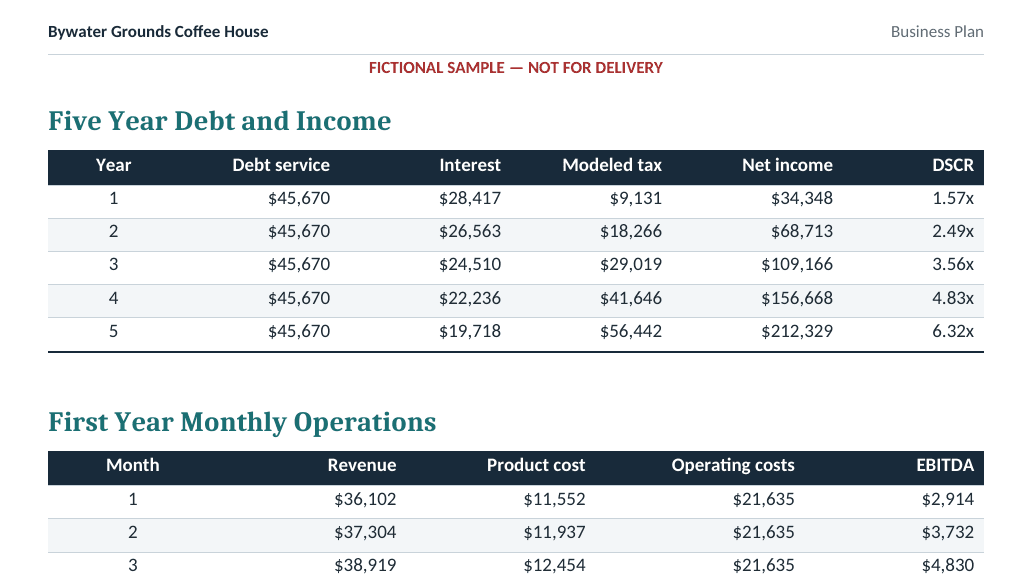
- 2Bywater sample, p. 11, Five Year Debt and Income, year 1 DSCR
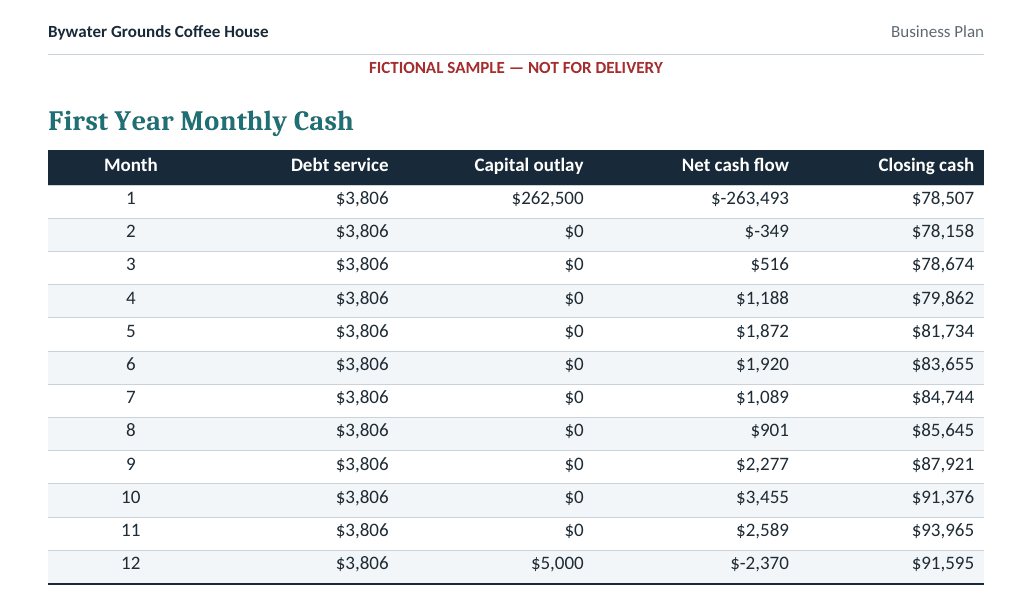
- 3Bywater sample, p. 12, First Year Monthly Cash, month 2 closing cash
- IncludedIntake
- You get: A saved intake you can come back to
- You answer plain questions about the business and attach the records you have. Estimates are fine; I’ll flag the ones that need support.You get: A saved intake you can come back to
- IncludedChecks
- You get: Five-year projections and first-year monthly schedules
- Software checks readiness, researches the market, builds the financial model, writes the draft and stress-tests it. Projected figures come from the model. Other figures need an owner statement or a named source.You get: Five-year projections and first-year monthly schedules
- IncludedBen’s review
- You get: A plan I’ve reviewed
- I read the whole plan and edit it before it reaches you, checking consistency, clarity, unresolved assumptions and unsupported claims.You get: A plan I’ve reviewed
- IncludedDelivery
- You get: Two consolidated revision rounds
- You get the plan as an editable DOCX and a PDF, with the source register, downside cases and lender questions.You get: Two consolidated revision rounds
- FlaggedIf the numbers don’t work
- When projected cash flow doesn’t cover the loan payments, the plan stops and is flagged for review instead of delivered. I’d rather tell you than have a lender tell you.
Fictional sample
Read the sample the way a lender would.
Bywater Grounds is a fictional coffee house. I built its plan with the same financial model and document renderer a real plan uses, so you can check the tables, the sources and the open conditions yourself.
What a weak spot looks like in the sample
- FlaggedA conditional conclusion
- The reference names the evidence still required before a real plan could be released.
- FlaggedResearch challenges the intake
- Named nearby competitors replace the unsupported claim that the neighborhood has no alternatives.
- FlaggedGaps named, not buried
- Costs identified but not yet quantified are listed as outstanding conditions.
Fictional reference. Not a live run of the service and not independently reviewed.
- 11.57x, the figure in the model above: Bywater sample, p. 11, Five Year Debt and Income, year 1 DSCR
- 2$78,158, the lowest cash balance: Bywater sample, p. 12, First Year Monthly Cash, month 2 closing cash
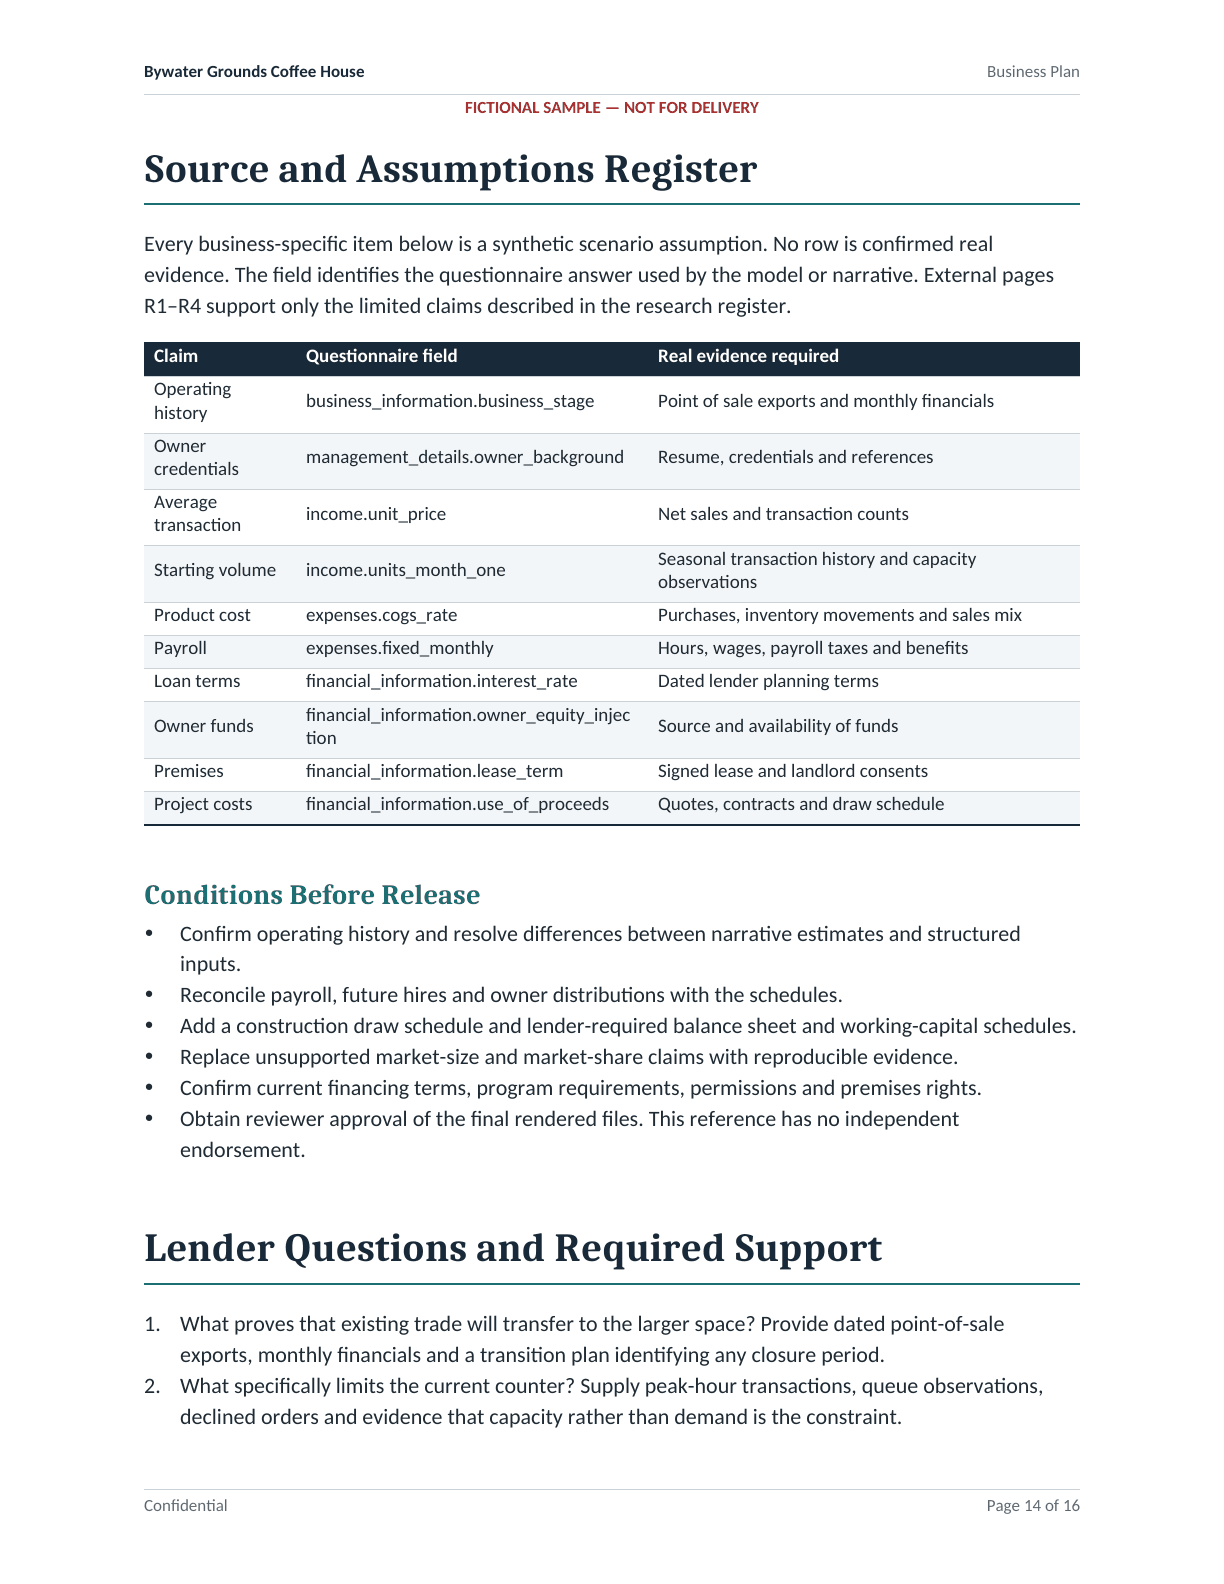
- 3What a real plan must document: Bywater sample, p. 14, Source and Assumptions Register, “Real evidence required” column
I review every plan before it reaches you.
I’m a technical founder and consultant. My background is building systems, not underwriting loans.
So I built this the way I’d build any system that has to be right. Your assumptions go through a financial model first, the plan quotes what the model computed, and every projected figure is tied back to the model before anything ships.
I read and edit every plan myself, for consistency, clarity and anything the model flagged as thin. I take a limited number of plans so each one gets my full attention.
Ben Hankins
Technical founder and consultant · I review every plan
A strong fit
- FitYou operate a US local service business.
- FitYou are seeking financing for a defined expansion.
- FitYou can share operating history and forecast assumptions.
Better served elsewhere
- Not a fitYou are still validating an idea or have no operating history.
- Not a fitYou need audited projections or independent market research.
- Not a fitYou need legal, tax, lending, or approval advice.
Pick the turnaround that fits your lender’s calendar.
Every tier covers one operating business and one financing goal. Faster tiers move you up the queue, and Extended trades some research depth and the final wording pass for the lowest price. I confirm fit and price before I take payment.
Included at every tier
- IncludedGuided intake and readiness check
- IncludedFive-year operating projections and first-year monthly schedules
- IncludedSource and assumptions register, downside cases, and lender questions
- IncludedProjected figures reconciled to the model, other figures to their sources
- IncludedMy review and edit before delivery
- IncludedEditable DOCX and shareable PDF
- IncludedTwo consolidated revision rounds
- Extended · 14 days
- $995
- You have time before you approach a lender and want the lowest cost.Narrower market research. You do the final wording pass yourself.
- Standard · 7 daysRecommended
- $1,495
- A good fit for an expansion package that is already taking shape.Full scope, delivered ready to hand to a lender.
- Priority · 3 days
- $1,995
- A lender meeting is on the calendar and the plan is the missing piece.Full scope. Your intake moves to the front of the queue.
- Rush · 24 hours
- $2,495
- A deadline lands tomorrow and the intake is already complete.Full scope, same day. Availability is confirmed before you pay.
Turnaround starts when I accept your intake as complete, not when you pay. I confirm rush availability before payment.
The fine print
What I can and can’t do for you
- What my review covers
Software supports drafting and quality checks, then I personally review and edit the plan before delivery. More
That review checks the final document for clarity, internal consistency, unresolved assumptions, and unsupported claims. It does not independently verify every fact you supply, so review every fact, assumption, and projection before sharing it.
Checks are performed on the information you supply and on identified sources. They test internal consistency—they do not independently verify that the underlying inputs are correct, and they do not predict lender approval.
See what the review checks- Advice and outcomes
- This is planning support, not legal, tax, accounting, investment, or lending advice. It does not guarantee financing or lender acceptance. Your lender, accountant, attorney and advisors make their own decisions.
- Your data
Do not submit Social Security numbers, bank or card numbers, passwords, medical records, or other sensitive personal data. More
Card details are entered on Stripe’s own checkout page and are never sent to this site or stored by it.
Your intake answers, uploaded evidence, and generated plan are processed to produce and deliver your plan and to support the service, including by the AI and infrastructure providers it runs on. Those providers apply their own retention rules; this is not zero-retention processing.
Deletion: you can request deletion at any time. Deleting a project schedules its records, uploaded documents, and generated files for removal after a 30-day recovery window, so an accidental request can be undone. Completed erasure depends on the scheduled retention job, so ask for confirmation rather than assuming it is immediate.
Read privacy and data handling- Payment
Orders open after launch checks are complete. More
When they do, payment is handled by Stripe on its own checkout page and the final amount is set on the server at checkout — these figures are here so you know the range before you get there.
- Revisions and refunds
Your turnaround begins when Ben accepts the intake as complete. More
Two consolidated revision rounds are included at every tier; each is one list submitted within seven days of delivery. Revisions refine the agreed plan. A new concept, audience, material data set, or custom analysis is new scope.
Fit and any applicable fee requirements are confirmed before work is accepted. A pre-acceptance scope mismatch or inability to deliver the agreed scope is canceled and refunded. Under the proposed service policy, a change of mind, business direction, or financing denial after the first complete draft does not qualify for a refund; the included revisions cover in-scope corrections. Mandatory legal remedies and required fee refunds take priority.
Read the service terms and refunds- SBA Form 159
Fees paid to a third party for help preparing an SBA loan application are itemized by the applicant on SBA Form 159. More
Every tier here is priced below the $2,500 threshold that brings additional fee review into that process. This is context, not lending or legal advice — confirm the specifics with your lender.
- Support
Reply to your access confirmation for help with sign-in, intake questions, file-delivery issues, or either included consolidated revision round. More
Support can help you use the service. Your financial and lending advisors should validate assumptions and loan decisions.
Tell me about the expansion you’re financing.
If it’s a fit, you get a turnaround and a confirmed price before anything else happens. If it isn’t, I’ll say so, and the sample is yours to keep.